
Appraisal Gap in Nashville: What Buyers Can Do When Value Comes In Low
An appraisal gap in Nashville leaves the buyer covering the difference when the appraisal comes in below the contract price. Options, risks and next steps.
An appraisal gap in Nashville appears when the lender's appraisal comes in below the contract price the buyer and seller already agreed on. Because most mortgages are sized against the lower of the purchase price and the appraised value, a low appraisal can force the buyer to bring more cash, renegotiate or walk away.
Why an appraisal gap matters to the loan
The Consumer Financial Protection Bureau says an appraisal is a professional opinion of the home's value, that appraisers must follow rules in arriving at that value, and that lenders are not allowed to interfere with the appraiser's judgment. The lender is required to send the borrower a copy of the appraisal.
Lenders generally will not finance more than the appraised value supports under the loan's loan-to-value rules. When the appraisal is lower than the sale price, the gap between those two numbers is cash the buyer must cover if the purchase price stays the same — or a reason to renegotiate. The CFPB calls buying a home for more than the appraised value very risky.
What Nashville buyers can do
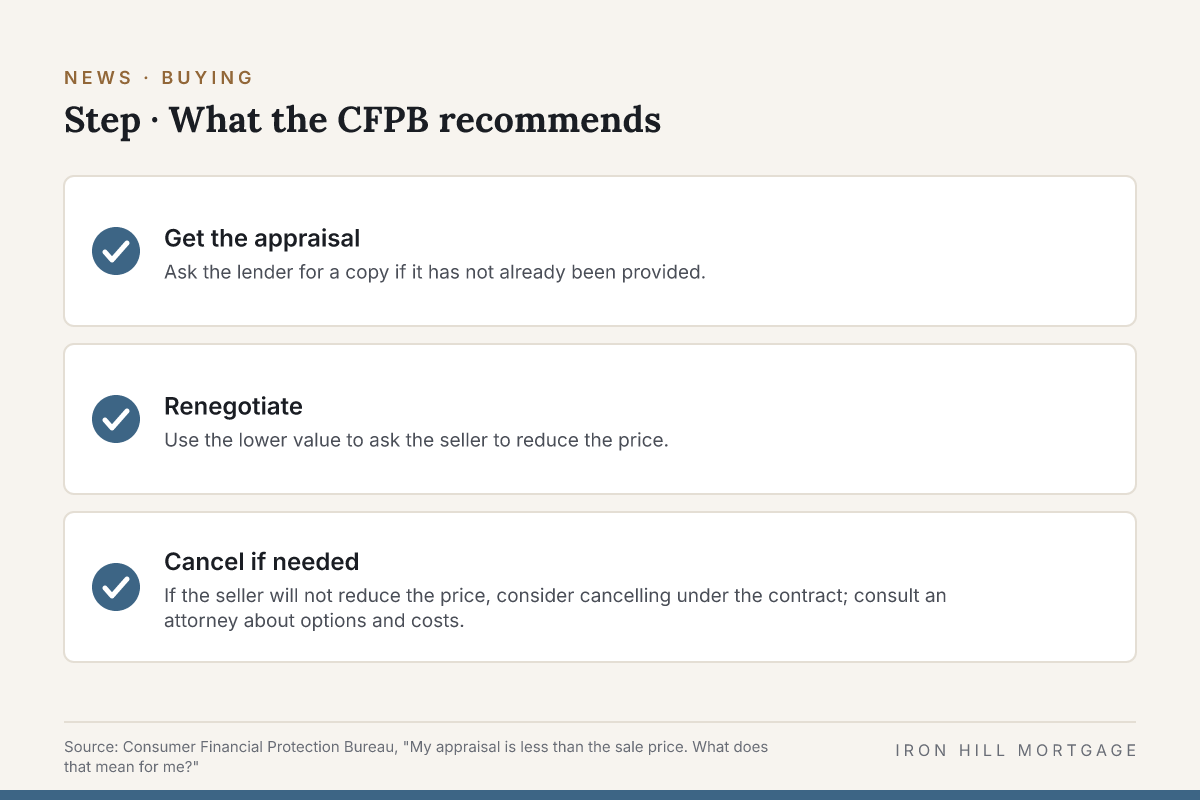
The CFPB's Ask CFPB guidance outlines a practical sequence:
| Step | What the CFPB recommends |
|---|---|
| Get the appraisal | Ask the lender for a copy if it has not already been provided. |
| Renegotiate | Use the lower value to ask the seller to reduce the price. |
| Cancel if needed | If the seller will not reduce the price, consider cancelling under the contract; consult an attorney about options and costs. |
Source: Consumer Financial Protection Bureau, "My appraisal is less than the sale price. What does that mean for me?"
Whether a buyer can exit without penalty depends on the purchase contract, including any appraisal contingency. Some offers waive that contingency; buyers who do so accept more of the gap risk themselves. Covering a gap in cash also changes the borrower's down payment and reserves picture for underwriting.
Appraisal rights and the rest of the file
Borrowers have rights to the appraisal and, in some cases, to request a reconsideration of value under agency and investor rules. The Iron Hill Brief's guide to mortgage appraisal rights covers those steps. A solid preapproval versus prequalification conversation before writing an offer can also clarify how much cash a buyer can bring if an appraisal comes in light.
None of this replaces advice from a real estate attorney or agent on a specific contract. It is a financing and risk framework for when Nashville contract prices and lender appraisals diverge.
Sources
- Consumer Financial Protection Bureau, "My appraisal is less than the sale price. What does that mean for me?" (last reviewed Sep. 11, 2024; accessed Nov. 6, 2026): https://www.consumerfinance.gov/ask-cfpb/my-appraisal-is-less-than-the-sale-price-what-does-that-mean-for-me-en-2007/