
FHA Loan Tennessee Guide: Credit, Down Payment and Loan Limits
An FHA loan in Tennessee allows 3.5% down with a credit score of 580 or higher. How occupancy, debt ratios, mortgage insurance and county limits shape it.
An FHA loan in Tennessee is a mortgage insured by the Federal Housing Administration, a part of the U.S. Department of Housing and Urban Development, and made by an FHA-approved lender. The insurance lets lenders accept a smaller down payment and a lower credit score than many conventional loans, in exchange for mortgage insurance premiums and limits on the size of the loan. The rules are federal, so they are the same in Nashville as in Memphis; what changes by county is the maximum loan amount.
What are the FHA loan requirements in Tennessee?
FHA ties the down payment to the borrower's credit score. According to the FDIC's Affordable Mortgage Lending Guide, which summarizes HUD's Section 203(b) program, a borrower with a credit score at or above 580 is eligible for maximum financing, a loan-to-value ratio of 96.5% on a purchase, which works out to a minimum down payment of 3.5%. A score between 500 and 579 limits the loan to 90% of value, and a score below 500 is not eligible for FHA-insured financing. Lenders may set higher minimums than HUD's, so requirements vary by lender.
The loan must be for a home the borrower will live in. The FDIC guide notes that the 203(b) program is limited to owner-occupied primary residences and can finance one- to four-unit homes, condominium units and certain other eligible property types. It is not restricted to first-time buyers.
Lenders also measure income against debts. HUD uses two ratios: the housing payment against effective income, which should not exceed 31% on a manually underwritten loan, and total monthly debts against income, which should not exceed 43%, according to the FDIC guide. Loans approved through FHA's automated scorecard are not held to those caps, and manually underwritten files above them need documented compensating factors.
How does FHA mortgage insurance work?
FHA loans carry two premiums: an upfront premium and an annual premium paid monthly. The Brief's guide to FHA mortgage insurance covers the current rates and how long borrowers pay them. Those premiums are the main cost to weigh against the smaller down payment.
What are the FHA loan limits in Tennessee?
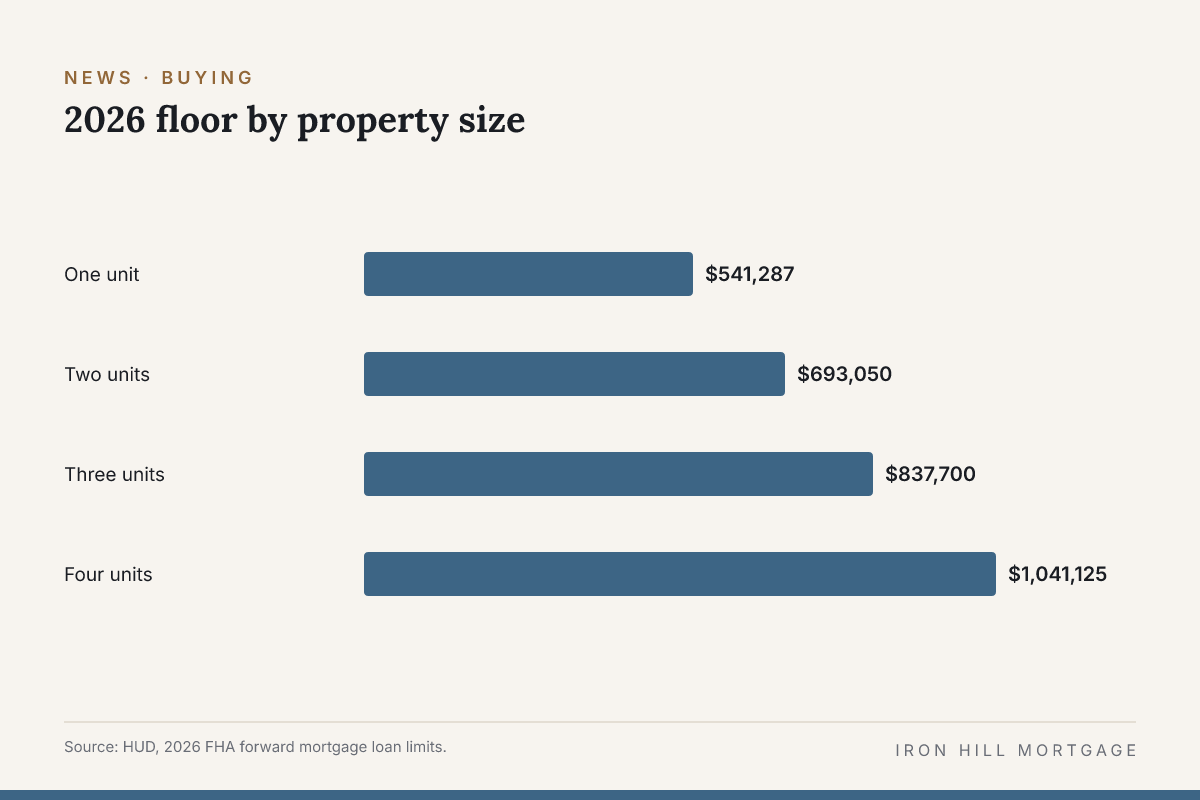
HUD sets FHA loan limits by county or metropolitan area each year. For case numbers assigned on or after Jan. 1, 2026, the one-unit limit runs from a low-cost floor of $541,287 to a high-cost ceiling of $1,249,125, according to HUD. Most counties sit at the floor; higher-cost areas receive limits between the floor and the ceiling based on local home prices.
| Property size | 2026 floor | 2026 ceiling |
|---|---|---|
| One unit | $541,287 | $1,249,125 |
| Two units | $693,050 | $1,599,375 |
| Three units | $837,700 | $1,933,200 |
| Four units | $1,041,125 | $2,402,625 |
Source: HUD, 2026 FHA forward mortgage loan limits.
The Brief's report on 2026 FHA loan limits lists county figures, including Davidson County. Iron Hill's FHA loans page outlines the program.
Frequently asked questions
What credit score is needed for an FHA loan in Tennessee?
HUD's minimum is 500, with 3.5% down available at 580 or higher and a 10% minimum down payment required from 500 to 579. Individual lenders may require higher scores.
Can an FHA loan be used for a rental property?
No. The program is for owner-occupied primary residences, though a borrower may buy a two- to four-unit home and live in one of the units.
Is an FHA loan only for first-time buyers?
No. The FDIC guide notes that FHA is often used by first-time buyers but has no special terms or restrictions tied to first-time status.
Sources
- U.S. Department of Housing and Urban Development, "HUD's Federal Housing Administration Announces 2026 Loan Limits," HUD No. 25-145, Dec. 11, 2025 (accessed Nov. 12, 2026): https://www.hud.gov/news/hud-no-25-145
- Federal Deposit Insurance Corporation, Affordable Mortgage Lending Guide, "203(b) Mortgage Insurance Program" (accessed Nov. 12, 2026): https://www.fdic.gov/resources/bankers/affordable-mortgage-lending-center/guide/part-1-docs/203b-mortgage-insurance-program.pdf