
Investment Property Mortgage Rates in Tennessee: Why Rentals Price Higher
Investment property mortgage rates in Tennessee run above weekly averages. See how Fannie Mae's rental-loan fees and down payment limits shape a quote.
Franklin, Tenn. — October 29, 2026 — Investment property mortgage rates in Tennessee generally run above the averages in weekly mortgage headlines, because the best-known benchmark tracks owner-occupied homes and Fannie Mae charges added fees on loans for rental properties. Freddie Mac's Primary Mortgage Market Survey put the average 30-year fixed rate at 7.32% as of Oct. 22, down from 7.40% a week earlier and up from 6.19% a year ago.
That survey describes its borrower profile as good to excellent credit, a 20% down payment and a home purchase loan on an owner-occupied, one-unit single-family property. A rental purchase falls outside that profile even when every other detail matches, so an investor's quote will usually differ from the headline average.
What drives investment property mortgage rates in Tennessee
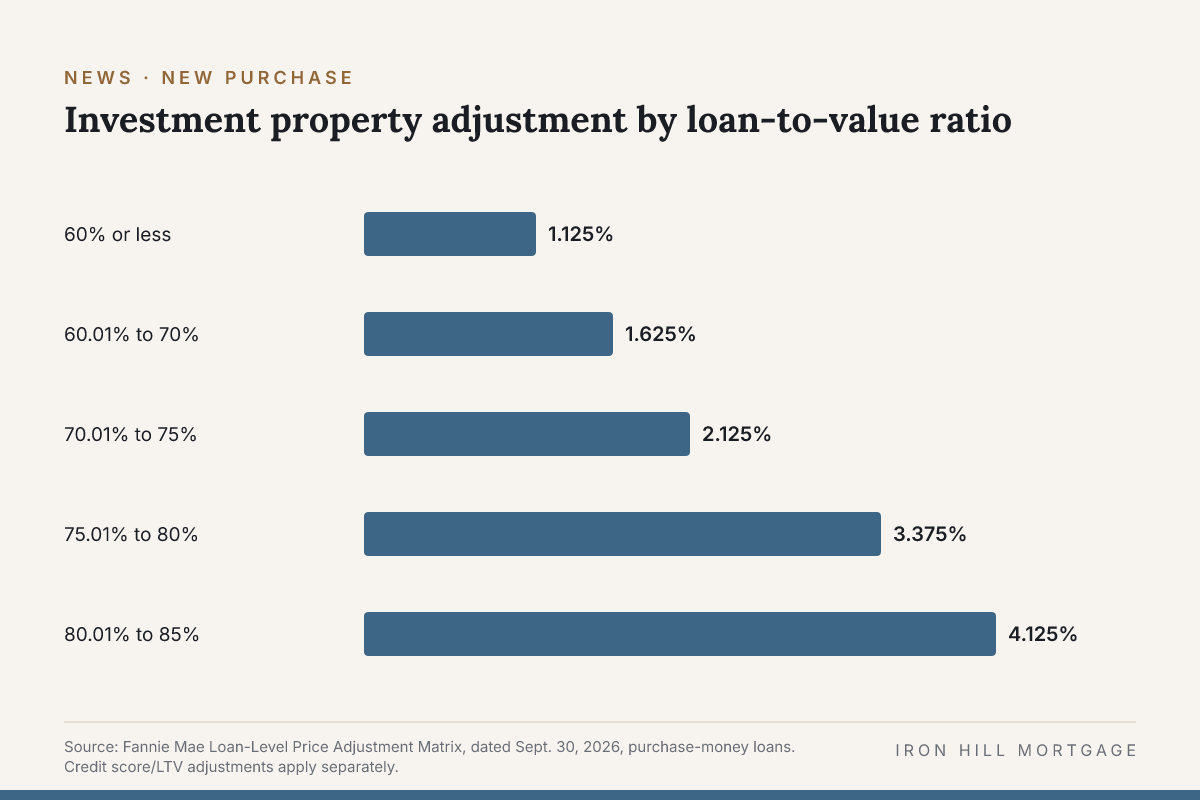
Fannie Mae, which buys conventional loans from lenders, publishes a Loan-Level Price Adjustment Matrix that sets upfront charges by loan feature. The charges are a percentage of the loan amount, and they add up: a loan can carry an adjustment for its credit score and loan-to-value ratio plus separate adjustments for features such as an investment property or a two- to four-unit building.
The investment-property adjustment on a purchase rises with the loan-to-value ratio:
| Loan-to-value ratio | Investment property adjustment | Additional adjustment, 2-4 units |
|---|---|---|
| 60% or less | 1.125% | 0.000% |
| 60.01% to 70% | 1.625% | 0.375% |
| 70.01% to 75% | 2.125% | 0.375% |
| 75.01% to 80% | 3.375% | 0.625% |
| 80.01% to 85% | 4.125% | 0.625% |
Source: Fannie Mae Loan-Level Price Adjustment Matrix, dated Sept. 30, 2026, purchase-money loans. Credit score/LTV adjustments apply separately.
The matrix is national, so a rental in Knoxville, Memphis or Murfreesboro falls under the same grid as one anywhere else. The credit score grid stacks on top: for a purchase with a term longer than 15 years and a loan-to-value ratio between 75.01% and 80%, the matrix lists 0.375% for a score of 780 or higher and 1.750% for a score from 680 to 699, before the investment-property charge.
Borrowers usually do not see these charges as a separate line. The Federal Housing Finance Agency, which oversees Fannie Mae and Freddie Mac, says a lender typically passes the cost of an upfront fee through to the borrower as a slightly higher interest rate, since borrowers tend to choose not to pay points.
How much down payment a rental purchase needs
Fannie Mae's Eligibility Matrix, dated Aug. 5, 2026, sets the maximum loan-to-value ratio for an investment property purchase underwritten through its Desktop Underwriter system at 85% for a one-unit property and 75% for two to four units.
Because the adjustment steps up at 60%, 70%, 75% and 80%, a larger down payment can move a loan into a lower bracket. Credit score, property type, loan term and the rate-lock period also affect the final quote, and the exact figures for a specific loan appear on the Loan Estimate.
Where DSCR loans fit
Conventional loans are one route. Many investors also look at DSCR loans, which are made outside the Fannie Mae and Freddie Mac grids and weigh a property's rental income against its debt payments rather than the borrower's personal income. Their pricing and terms are set by each lender and vary. Iron Hill Brief's DSCR loan Tennessee guide explains how lenders measure that ratio, and the DSCR calculator can help an investor test a property's numbers before applying. The overview of DSCR loans covers how the program works for Tennessee rentals.
Working on a Tennessee rental? Talk with an Iron Hill loan advisor: text Ashley at 615-949-4780 or book a time here. Iron Hill Mortgage | NMLS #1946451.
Business-purpose loans for investment property only. Not for personal, family or household use. Subject to approval. Equal Housing Opportunity.
Sources
- Freddie Mac, Primary Mortgage Market Survey, results as of Oct. 22, 2026, and PMMS FAQ on borrower profile (accessed Oct. 28, 2026): https://www.freddiemac.com/pmms
- Fannie Mae, Loan-Level Price Adjustment Matrix, dated Sept. 30, 2026 (accessed Oct. 28, 2026): https://singlefamily.fanniemae.com/media/9391/display
- Fannie Mae, Eligibility Matrix, dated Aug. 5, 2026 (accessed Oct. 28, 2026): https://singlefamily.fanniemae.com/media/20786/display
- Federal Housing Finance Agency, "Guarantee Fees History" (accessed Oct. 28, 2026): https://www.fhfa.gov/policy/guarantee-fees