
How Much House Can I Afford in Nashville? Debt, Rates and Medians
How much house can I afford in Nashville depends on debt-to-income limits, rates and local prices. What lenders count and how county medians compare.
Franklin, Tenn. — November 4, 2026
How much house can I afford in Nashville is a question lenders answer mainly with one number: the share of a buyer's gross monthly income that would go to debt payments, including the new mortgage. Home prices, interest rates, property taxes and insurance all feed into that payment, so the answer differs from one household and one county to the next.
How do lenders decide how much house you can afford?
The Consumer Financial Protection Bureau defines the debt-to-income ratio, or DTI, as all monthly debt payments divided by gross monthly income, and notes that different loan products and lenders have different DTI limits.
For conventional loans sold to Fannie Mae, the Selling Guide sets a maximum total DTI of 36% for manually underwritten loans, which can rise to 45% if the borrower meets credit score and reserve requirements. Loans underwritten through Fannie Mae's automated Desktop Underwriter system can go up to 50%. Those are ceilings, not targets, and lenders may apply stricter limits of their own.
The Iron Hill Brief's guide to the debt-to-income ratio walks through which debts count and how the ratio is calculated.
How much house can I afford in Nashville at today's rates?
The interest rate sets how much of a monthly payment goes to interest, so the same payment supports a smaller loan when rates are higher. The average 30-year fixed rate was 7.24% in the week ending Oct. 29, according to Freddie Mac's Primary Mortgage Market Survey, down from 7.32% a week earlier and up from 6.17% a year earlier. The 15-year fixed averaged 6.60%.
Freddie Mac's survey reflects borrowers with strong credit putting 20% down on a single-family home they will live in. A buyer's own rate depends on credit, down payment, loan type and the lender.
Home values and owner costs around Nashville
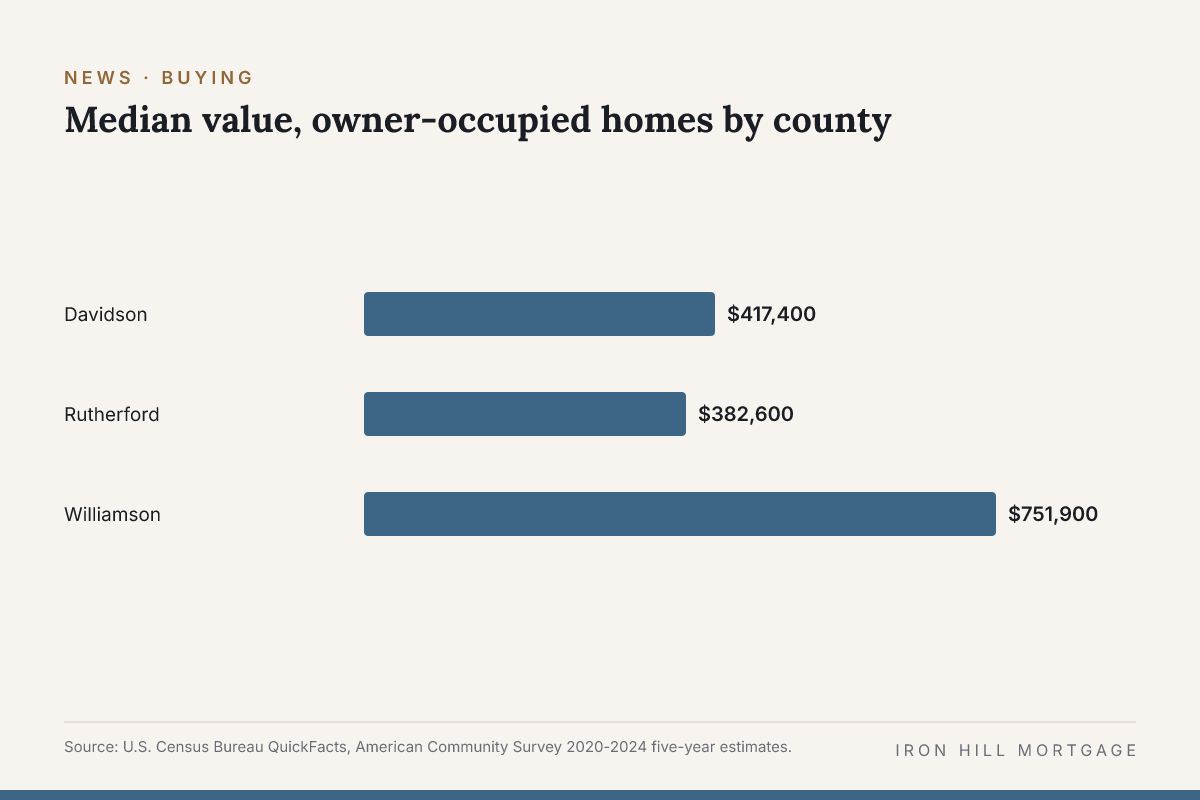
Census Bureau survey figures give a broad picture of what homes are worth and what owners with a mortgage pay each month in Nashville and two neighboring counties.
| County | Median value, owner-occupied homes | Median monthly owner costs, with a mortgage | Owner-occupied rate |
|---|---|---|---|
| Davidson | $417,400 | $1,910 | 52.8% |
| Rutherford | $382,600 | $1,745 | 64.8% |
| Williamson | $751,900 | $2,642 | 78.8% |
Source: U.S. Census Bureau QuickFacts, American Community Survey 2020-2024 five-year estimates.
These are five-year survey medians for existing homeowners, including many who bought years ago, so they are not estimates of what a buyer would pay today. Monthly owner costs include the mortgage, property taxes, insurance and utilities. The Iron Hill Brief's Davidson County housing market report covers recent sales conditions in Nashville.
Frequently asked questions
Does a preapproval tell me how much house I can afford? A preapproval shows how much a lender is tentatively willing to lend based on the information and documents reviewed, which is not the same as the payment a household is comfortable with. The CFPB notes that DTI is one way lenders measure the ability to manage monthly payments.
What payment should I use to estimate a price range? The full housing payment, including principal, interest, property taxes, homeowners insurance and any association dues, is what lenders count. The home affordability calculator estimates a price range from income, debts and down payment.
Do Nashville's county differences matter? Yes. Property taxes and insurance vary by county and city, so two homes at the same price can carry different monthly payments.
Sources
- Freddie Mac, Primary Mortgage Market Survey, week of Oct. 29, 2026 (accessed Nov. 3, 2026): https://www.freddiemac.com/pmms
- Consumer Financial Protection Bureau, "What is a debt-to-income ratio?" (last reviewed Aug. 28, 2023; accessed Nov. 3, 2026): https://www.consumerfinance.gov/ask-cfpb/what-is-a-debt-to-income-ratio-en-1791/
- Fannie Mae Selling Guide, B3-6-02, "Debt-to-Income Ratios" (accessed Nov. 3, 2026): https://selling-guide.fanniemae.com/sel/b3-6-02/debt-income-ratios
- U.S. Census Bureau, QuickFacts: Davidson County, Williamson County and Rutherford County, Tennessee (American Community Survey 2020-2024 five-year estimates; accessed Nov. 3, 2026): https://www.census.gov/quickfacts/fact/table/davidsoncountytennessee,williamsoncountytennessee,rutherfordcountytennessee/HSG445224