
Investment Property Down Payment: What Fannie Mae Rules Require
The minimum investment property down payment on a conventional loan is 15% for one unit and 25% for two to four. Why gifts don't count and reserves matter.
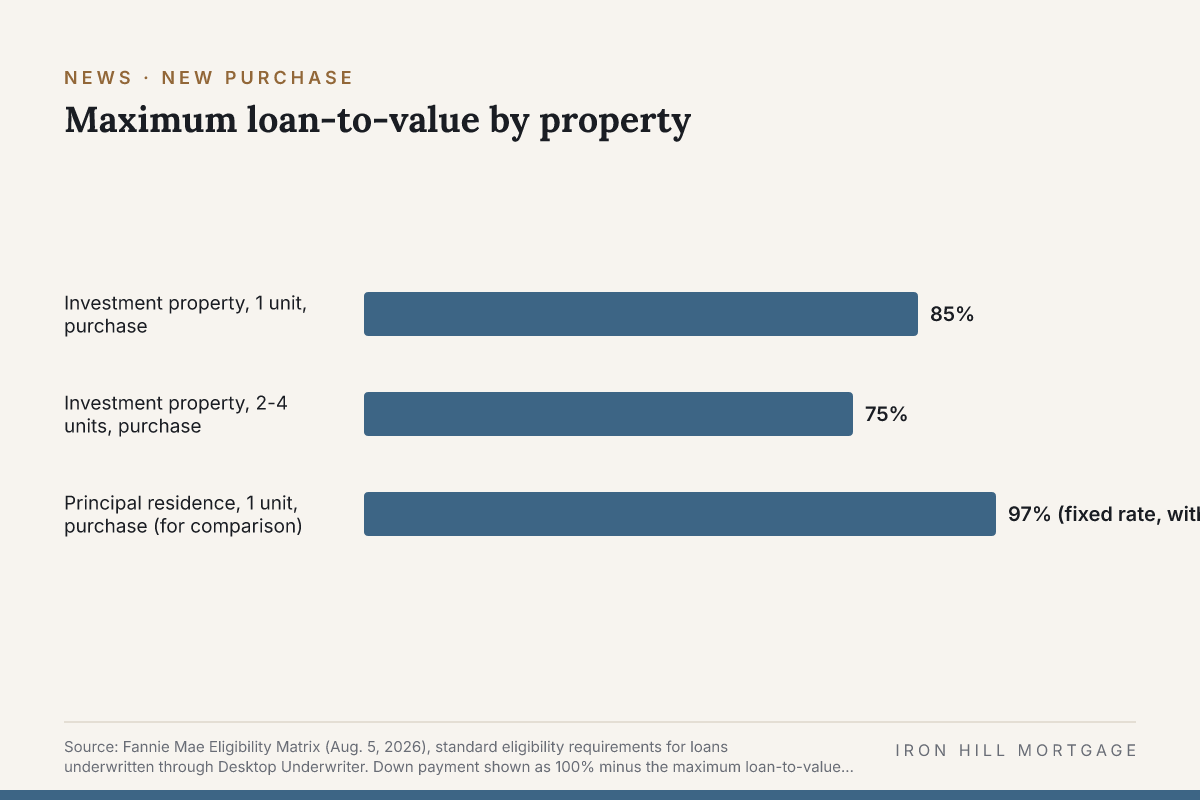
The minimum investment property down payment on a conventional loan sold to Fannie Mae is 15% for a one-unit rental and 25% for a property with two to four units, based on the maximum loan-to-value ratios in Fannie Mae's eligibility matrix. Those minimums are higher than for a home the buyer will live in, and the rules on where the money can come from are stricter too.
Investment property down payment minimums
| Property | Maximum loan-to-value | Minimum down payment |
|---|---|---|
| Investment property, 1 unit, purchase | 85% | 15% |
| Investment property, 2-4 units, purchase | 75% | 25% |
| Principal residence, 1 unit, purchase (for comparison) | 97% (fixed rate, with conditions) | 3% |
Source: Fannie Mae Eligibility Matrix (Aug. 5, 2026), standard eligibility requirements for loans underwritten through Desktop Underwriter. Down payment shown as 100% minus the maximum loan-to-value ratio.
The matrix applies to fixed-rate and adjustable-rate loans alike for investment purchases. Fannie Mae notes that some transactions have exceptions, and individual lenders can set stricter limits than the matrix allows.
Why gifts don't count toward a rental down payment
Fannie Mae allows personal gifts from relatives and certain other donors on loans for a principal residence or second home, but its Selling Guide says gifts are not allowed on an investment property. On a conventional rental purchase, that means the down payment and closing funds generally have to come from the borrower's own documented assets.
Reserves on an investment property purchase
Beyond the down payment, Fannie Mae's automated underwriting requires six months of reserves for an investment property transaction, measured in months of the new loan's principal, interest, taxes, insurance and association dues. Investors who already own other financed properties must also hold additional reserves based on the unpaid balances of those other mortgages:
- 2% of the combined balance for one to four financed properties
- 4% for five to six
- 6% for seven to 10 (automated underwriting only)
The subject property and the borrower's own home are not counted in that combined balance.
Down payment on a DSCR loan
Debt service coverage ratio loans are business-purpose loans that fall outside Fannie Mae's conventional eligibility matrix, so down payment and reserve requirements are set by each lender and program and vary. The Iron Hill Brief's DSCR loan Tennessee guide explains how those loans measure a rental's income against its payment, its explainer on investment property mortgage rates in Tennessee covers why rental loans are priced above owner-occupied loans, and the overview of DSCR loans covers how the program works for Tennessee rentals.
Working on a Tennessee rental? Talk with an Iron Hill loan advisor: text Ashley at 615-949-4780 or book a time here. Iron Hill Mortgage | NMLS #1946451.
Business-purpose loans for investment property only. Not for personal, family or household use. Subject to approval. Equal Housing Opportunity.
Sources
- Fannie Mae, Eligibility Matrix (Aug. 5, 2026; accessed Oct. 30, 2026): https://singlefamily.fanniemae.com/media/20786/display
- Fannie Mae Selling Guide, B3-4.3-04, "Personal Gifts" (02/04/2026; accessed Oct. 30, 2026): https://selling-guide.fanniemae.com/sel/b3-4.3-04/personal-gifts
- Fannie Mae Selling Guide, B3-4.1-01, "Minimum Reserve Requirements" (08/07/2024; accessed Oct. 30, 2026): https://selling-guide.fanniemae.com/sel/b3-4.1-01/minimum-reserve-requirements