
Spec Home Construction Loan in Tennessee: How Draws and Exits Work
A spec home construction loan in Tennessee funds a builder's unsold home in stages tied to inspections. How draws, interest reserves and the exit work.
A spec home construction loan in Tennessee finances a house a builder starts before there is a buyer under contract, with the money released in stages as the work is inspected rather than all at closing. Because the loan is repaid when the finished home sells, lenders look closely at the budget, the builder's own cash in the project and how quickly homes are selling in that market.
How a spec home construction loan in Tennessee is structured
The Office of the Comptroller of the Currency's handbook for bank examiners says construction loans that finance multiple homes are ordinarily structured so repayment follows unit sales, with the builder paying down the loan as each home sells and the lender releases its lien. For builders putting up several homes, the handbook says loan agreements typically allow a limited number of speculative units and models, with the limit set partly by the expected absorption rate, or how fast homes in the area are selling.
Lenders size these loans against both cost and value. The handbook says prudent policies cap the loan as a percentage of project cost, known as loan-to-cost, in addition to loan-to-value, so the builder keeps cash at risk throughout the build. Exact ratios, fees and terms vary by lender and program.
How construction draws work
Construction money is paid out in draws. According to the OCC handbook, residential and smaller construction loans usually follow a standard payment plan, most commonly five equal installments, with the first four released as the home reaches agreed stages verified by an inspection and the last paid only after the legal period for mechanics' liens has run.
Before funding a draw, lenders typically:
- confirm through an inspection that the work billed has been completed
- check that the remaining budget is enough to finish the home
- update the title to confirm no new liens have been filed by contractors or suppliers
Many construction loans also carry an interest reserve, a budgeted amount used to pay interest during the build and until the home sells. The handbook notes that a depleted reserve often signals construction delays or a change in market conditions, and that lenders generally then ask the borrower to put in more cash.
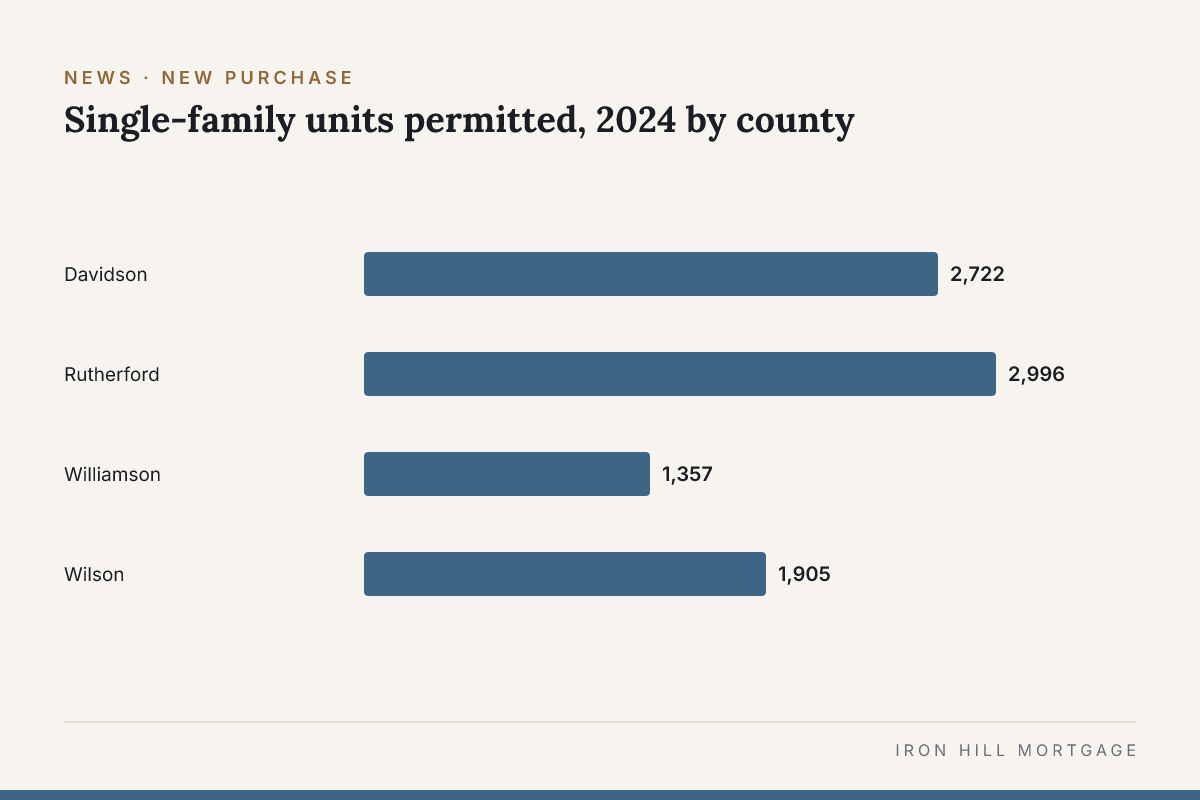
Single-family permits in Middle Tennessee
Census Bureau permit data show how many new single-family homes were authorized in Nashville and three neighboring counties.
| County | Single-family units permitted, 2024 | Single-family units permitted, 2025 | Change | Average reported construction value per unit, 2025 |
|---|---|---|---|---|
| Davidson | 2,722 | 2,739 | +0.6% | $313,536 |
| Rutherford | 2,996 | 2,533 | -15.5% | $271,702 |
| Williamson | 1,357 | 1,286 | -5.2% | $821,136 |
| Wilson | 1,905 | 1,723 | -9.6% | $312,725 |
Source: U.S. Census Bureau, Building Permits Survey, county annual data for 2024 and 2025 (estimates with imputation). Average construction value is the total reported permit valuation for one-unit buildings divided by units permitted; it reflects construction cost as reported on permits, not land or sale prices.
Permits for new single-family homes fell in 2025 in Rutherford, Williamson and Wilson counties and were roughly flat in Davidson. Permit counts measure homes authorized, not homes sold, so builders and lenders typically pair them with local sales and inventory data when judging absorption.
Planning the exit
Because a spec loan is short-term, the plan for paying it off matters as much as the build. The usual exit is the sale of the finished home. If a home does not sell as planned, some investors keep it as a rental and refinance into a longer-term rental loan, and others use short-term bridge financing while they wait for a buyer. Each path has its own qualification standards, which vary by lender.
The Iron Hill Brief's fix and flip loan Tennessee guide covers short-term financing for renovation projects, and the overview of construction loans explains how ground-up financing works for Tennessee investors.
Working on a Tennessee rental? Talk with an Iron Hill loan advisor: text Ashley at 615-949-4780 or book a time here. Iron Hill Mortgage | NMLS #1946451.
Business-purpose loans for investment property only. Not for personal, family or household use. Subject to approval. Equal Housing Opportunity.
Sources
- Office of the Comptroller of the Currency, Comptroller's Handbook, "Commercial Real Estate Lending," Version 2.0 (March 2022, updated March 20, 2025; accessed Nov. 3, 2026): https://occ.gov/publications-and-resources/publications/comptrollers-handbook/files/commercial-real-estate-lending/pub-ch-commercial-real-estate.pdf
- U.S. Census Bureau, Building Permits Survey, County ASCII file, 2025 annual (accessed Nov. 3, 2026): https://www2.census.gov/econ/bps/County/co2025a.txt
- U.S. Census Bureau, Building Permits Survey, County ASCII file, 2024 annual (accessed Nov. 3, 2026): https://www2.census.gov/econ/bps/County/co2024a.txt