
Delayed Financing Investment Property Rules: Cash Back After an All-Cash Buy
Delayed financing investment property rules let a cash buyer refinance a rental within six months of purchase, if Fannie Mae's documentation tests are met.
Delayed financing investment property rules give an investor who bought a rental with cash a defined path to borrow against it soon after closing, instead of waiting out the usual ownership period for a cash-out refinance. Fannie Mae's Selling Guide calls this the delayed financing exception, and it sets out what must be documented before the new loan can close.
How delayed financing on an investment property works
A standard cash-out refinance sold to Fannie Mae generally requires at least one borrower to have been on title to the property for six months before the new loan is disbursed, according to the Selling Guide. The delayed financing exception lifts that waiting period for borrowers who bought the property within the past six months, measured from the purchase date to the disbursement date of the new mortgage, provided the purchase involved no mortgage financing.
Cash buyers often use the exception to compete for a property without a financing contingency and then rebuild their cash position afterward. The new loan is still treated as a cash-out refinance: the Selling Guide says all other cash-out eligibility requirements apply and cash-out pricing is applicable.
What lenders document under the delayed financing exception
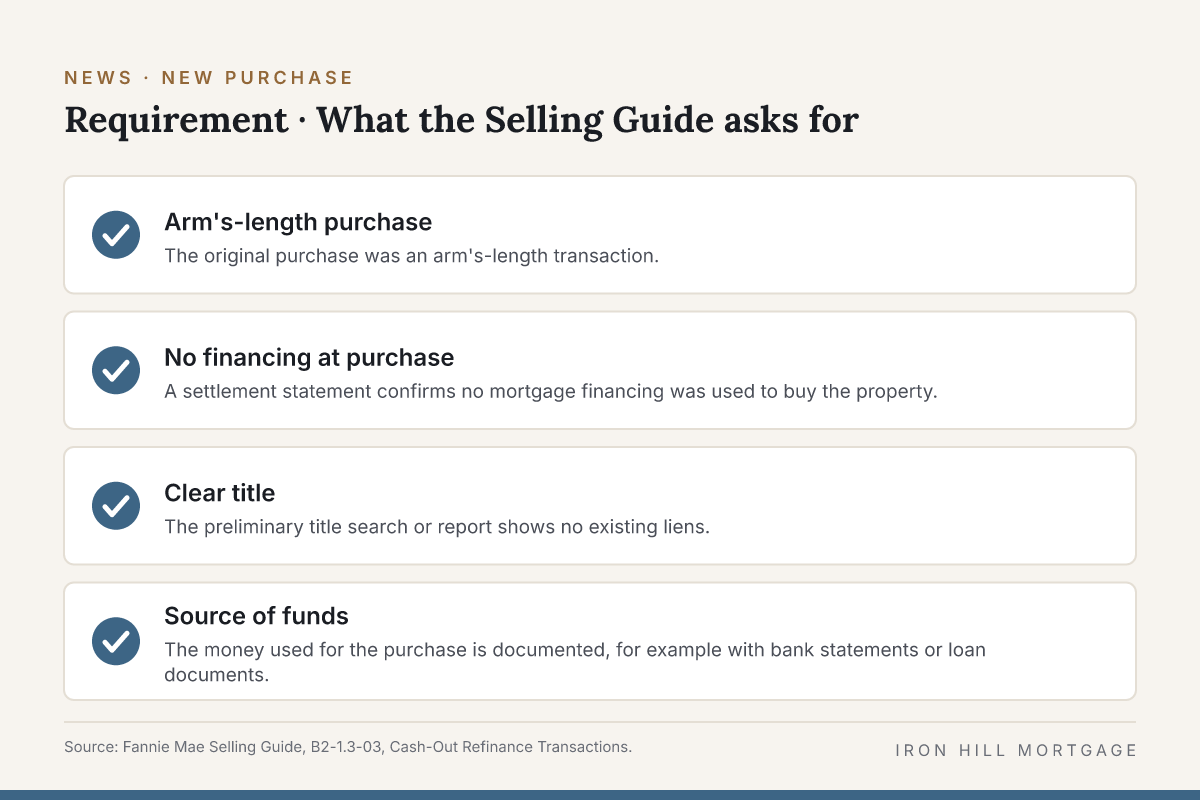
Fannie Mae lists several conditions for the exception:
| Requirement | What the Selling Guide asks for |
|---|---|
| Arm's-length purchase | The original purchase was an arm's-length transaction. |
| No financing at purchase | A settlement statement confirms no mortgage financing was used to buy the property. |
| Clear title | The preliminary title search or report shows no existing liens. |
| Source of funds | The money used for the purchase is documented, for example with bank statements or loan documents. |
| Loan amount cap | The new loan is no more than the documented initial investment plus financed closing costs, prepaid fees and points, within the maximum cash-out loan-to-value ratios based on the current appraised value. |
| Who bought it | A natural person, certain eligible trusts, or an LLC or partnership the borrowers own 100%. |
Source: Fannie Mae Selling Guide, B2-1.3-03, Cash-Out Refinance Transactions.
Two further limits matter for planning. If the purchase was paid for with an unsecured loan or a loan secured by another asset, the refinance proceeds must go toward paying off or paying down that loan, and any remaining payment on it counts in the debt-to-income ratio. Gift funds used for the purchase may not be reimbursed from the new loan.
Delayed financing compared with other options
The delayed financing exception applies to loans delivered to Fannie Mae. Business-purpose lenders that offer rental-income loans, such as DSCR loans, set their own seasoning and cash-out rules, which vary by lender. For a short-term need between a purchase and permanent financing, investors sometimes look at bridge loans instead. The Brief's guide to investment property down payments covers how much equity lenders typically expect on a financed rental purchase, and the home equity calculator can help estimate equity in a property an investor already owns.
Frequently asked questions
How soon after an all-cash purchase can an investor use delayed financing? Under Fannie Mae's Selling Guide, the exception covers properties purchased within the past six months, so the usual six-month ownership requirement does not apply once the documentation requirements are met.
Can an investor take out more than the purchase price? Not under the exception. The new loan amount is capped at the documented initial investment plus financed closing costs, prepaid fees and points, and it must also fit within the maximum cash-out loan-to-value ratio for the current appraised value.
Does buying in an LLC rule out delayed financing? Not necessarily. The Selling Guide allows the original purchase to have been made by an LLC or partnership in which the borrowers have 100% ownership, though the borrowers on the new loan must still meet Fannie Mae's borrower eligibility requirements.
Working on a Tennessee rental? Talk with an Iron Hill loan advisor: text Ashley at 615-949-4780 or book a time here. Iron Hill Mortgage | NMLS #1946451.
Business-purpose loans for investment property only. Not for personal, family or household use. Subject to approval. Equal Housing Opportunity.
Sources
- Fannie Mae Selling Guide, B2-1.3-03, "Cash-Out Refinance Transactions" (published Dec. 10, 2025; accessed Nov. 5, 2026): https://selling-guide.fanniemae.com/sel/b2-1.3-03/cash-out-refinance-transactions